Rent VAT rules for Kenya landlords have become one of the most consequential compliance issues in Kenyan property investment, and the rules are widely misunderstood. The Kenya Revenue Authority has clarified the position through a series of court decisions and regulatory guidelines, but confusion persists among landlords who own both residential and commercial property.
The core question is simple: when does a landlord need to charge VAT on rent? The answer depends on three variables — whether the property is residential or commercial, whether annual taxable turnover exceeds KSh 5 million, and whether the tenancy falls within the definition of a hotel or serviced accommodation. A landlord who gets this wrong faces backdated VAT assessments, penalties, and interest. Understanding the rent VAT rules for Kenya landlords is therefore not an academic exercise. It determines whether a landlord can operate without a retrospective tax liability.
The Statutory Framework: VAT Act and the First Schedule
The rent VAT rules for Kenya landlords framework rests on the Value Added Tax Act, Cap 476, and specifically Paragraph 8 of Part II of the First Schedule. That paragraph exempts “supply by way of sale, renting, leasing, hiring, letting of land or residential premises” from VAT. The exemption applies to two categories: land, and residential premises. Commercial premises are conspicuously absent from the exemption.
This distinction has been the subject of significant litigation in Kenya. In Kenya Revenue Authority v Ndegwa [2025] KECA 510 (KLR), the Court of Appeal clarified that only land and residential premises are VAT exempt, not commercial buildings. The court held that the definition of “land” in Article 260 of the Constitution allows the meaning to vary depending on context, and that for tax purposes, buildings on land could be treated independently and subjected to tax separately. The court found that the supply of any building that is not occupied as a residence is not exempt from VAT.
Any landlord researching rent VAT rules for Kenya landlords should understand that the exemption applies to residential tenancies, not to commercial ones. A shop, office, godown, or warehouse let to a business is a taxable supply. A residential apartment let to a family is an exempt supply.
The KSh 5 Million Registration Threshold
The rent VAT rules for Kenya landlords conversation must address the registration threshold, because it determines when VAT obligations begin. Under Section 34 of the VAT Act, any person who has supplied or expects to supply taxable goods or services with a value of KSh 5 million or more in a period of twelve months is required to register for VAT within thirty days of becoming liable for registration.
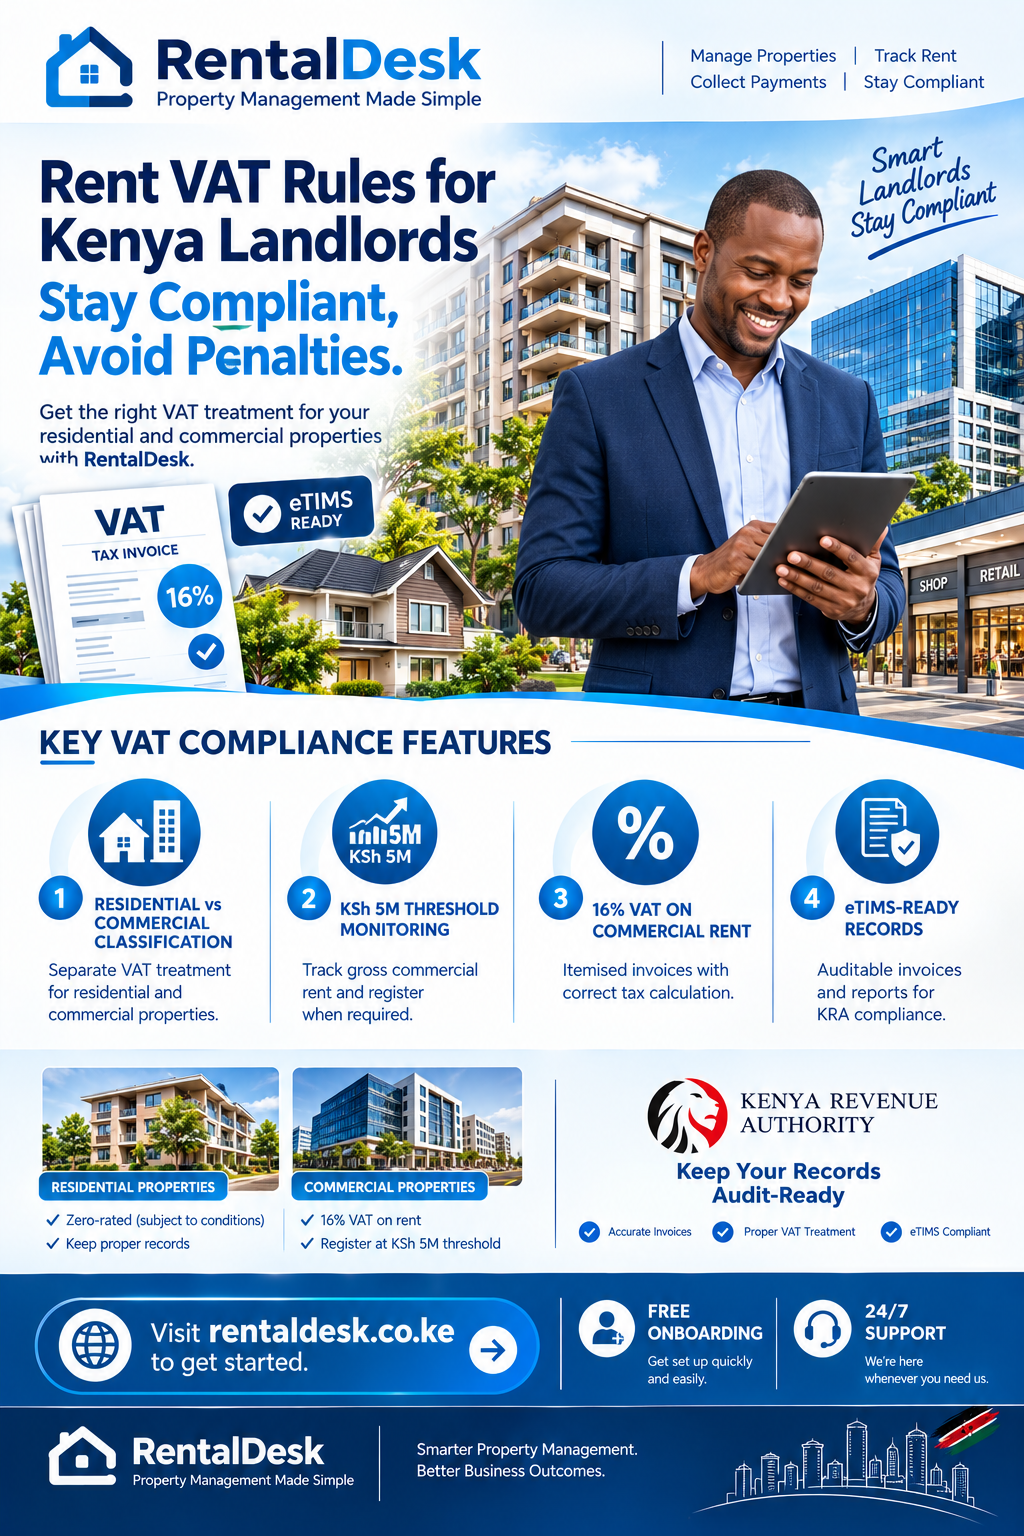
For landlords, the threshold applies to gross commercial rental income, not residential rental income. This is a critical distinction. Residential rent is exempt from VAT, and exempt income does not count toward the VAT registration threshold. A landlord earning KSh 4 million annually from commercial rent and KSh 2 million from residential rent has not exceeded the threshold for VAT registration, because only the commercial rent is a taxable supply.
A landlord whose gross commercial rental income touches or is projected to exceed KSh 5 million within a twelve-month period must register for VAT immediately. The Kenya Revenue Authority has made clear that once the threshold is crossed, registration is compulsory. A person who is already registered for VAT will not be required to register afresh for rental income but will charge tax on rental income even if rental income does not exceed KSh 5 million.
Any landlord evaluating rent VAT rules for Kenya landlords should monitor gross commercial invoicing monthly. If the portfolio is scaling toward the KSh 5 million milestone, proactive registration is essential. The consequences of crossing the threshold without registering are severe. KRA will backdate the 16% VAT liability, and the landlord will be forced to pay millions out of pocket for tax that was never collected from tenants, alongside late-payment penalties and compounding interest.
The 16% VAT Rate on Commercial Rent
The rent VAT rules for Kenya landlords framework applies a standard VAT rate of 16% to commercial rental income for landlords who have exceeded the threshold. This means the landlord must charge an additional 16% VAT on top of the base rent.
The practical effect on a commercial tenancy is straightforward. If a tenant pays KSh 100,000 per month in base rent, the landlord must charge KSh 116,000, remitting KSh 16,000 to KRA and retaining KSh 100,000. The tenant, if registered for VAT, can deduct the input tax charged on rent in their monthly return. This makes commercial rent VAT neutral for VAT-registered tenants, but it increases the effective cost for tenants who are not registered for VAT and cannot claim the input credit.
In Sayani Investments Limited v Commissioner of Legal Services & Board Coordination, the Tax Appeals Tribunal held that the sale of land, including land with a structure, is exempt from VAT under Paragraph 8. But the Tribunal also noted that the letting of residential premises is VAT-exempt, while the letting of commercial premises is subject to VAT. The distinction between sale and letting is important. Sale of land and residential premises is exempt. Letting of residential premises is exempt. Letting of commercial premises is taxable.
Any landlord seeking clarity on rent VAT rules for Kenya landlords must understand that the 16% VAT applies to commercial rent for landlords who have crossed the registration threshold. It does not apply to residential rent, regardless of the amount.
Residential Rent: The Exemption and Its Limits
The rent VAT rules for Kenya landlords conversation must address residential rent, because it is where the exemption is most valuable and most misunderstood. The supply of residential premises by way of renting, leasing, hiring, or letting is exempt from VAT under Paragraph 8 of Part II of the First Schedule.
But the definition of “residential premises” has limits. Hotel accommodation is excluded from the definition of residential premises under the Income Tax Act. The VAT Act defines a “hotel” to include service flats, service apartments, holiday cottages, and villas. The exception is a lease or licence of not less than one month where the lessee cannot terminate without penalty. This distinction has become increasingly important as short-term rentals and Airbnb-style accommodation have grown in Kenya.
If a landlord lets a furnished apartment to a guest for three, five, or twenty nights, the relationship is not a landlord-tenant relationship. It is a hotel-guest relationship. The income is subject to VAT at 16% once annual turnover exceeds KSh 5 million. A guest who books for a few nights and cancels freely is not a tenant. A tenant who occupies a unit monthly with a longer-term commitment is a residential tenant, and the rent is exempt.
Any landlord studying rent VAT rules for Kenya landlords must classify each tenancy correctly. A landlord who owns a block with shops downstairs, residential flats upstairs, and an Airbnb unit has three tax computations: commercial rent, residential rent, and Airbnb.
Mixed-Use Properties: Apportionment and Allocation
The rent VAT rules for Kenya landlords conversation must address mixed-use properties, because they create the most complex VAT compliance challenges. Where a building is used for both residential and non-residential purposes, tax is only chargeable on the rental of the portion used for non-residential purposes. The determination of whether rental income is taxable is based on the purposes to which that building or part of it is put.
This means the landlord must apportion income between residential and commercial components. If a building generates KSh 10 million annually in total rent, with KSh 6 million from commercial units and KSh 4 million from residential units, only the commercial rent counts toward the VAT registration threshold. If the KSh 6 million exceeds the threshold, the landlord must register for VAT and charge 16% on the commercial rent.
Where a registered person supplies both residential and non-residential property in the same building, the registered person will be required to apportion the input tax on the basis of the use of the premises. This means the landlord cannot claim input VAT on costs relating to the residential portion, but can claim input VAT on costs relating to the commercial portion.
Any landlord navigating rent VAT rules for Kenya landlords should maintain clear records of which units are residential and which are commercial. The classification determines the VAT treatment, and misclassification creates retrospective liability.
Input Tax Deductions: What Landlords Can Reclaim
The rent VAT rules for Kenya landlords conversation must address input tax, because it is where VAT-registered landlords recover some of the cost. A person registered for the supply of rental services is entitled to claim relief of tax incurred in the construction of commercial buildings or civil works, but not on the purchase of the building, as the sale of buildings is exempt.
For ongoing operations, the landlord can deduct the VAT paid on property expenditures such as legal fees, security services, electricity, repairs, and maintenance from the VAT collected from tenants. The net amount — output tax minus input tax — is what the landlord remits to KRA.
But input tax recovery is not unlimited. Input tax cannot be claimed on expenses relating to exempt supplies. If the landlord has both commercial and residential units, the input tax must be apportioned. Tax relating to exempt supplies is not deductible, either directly or upon apportionment with taxable supplies.
Any landlord reviewing rent VAT rules for Kenya landlords should confirm that input tax claims are limited to the commercial portion of the portfolio and that the documentation requirements are met. A valid tax invoice is required for every input tax claim, and the claim must be made within six months of the tax becoming due.
Filing and Payment Obligations
The rent VAT rules for Kenya landlords framework imposes monthly filing and payment obligations on registered landlords. The landlord must file VAT returns and remit the collected tax via the iTax Portal by the 20th day of every subsequent month.
The tax point — the time at which VAT becomes chargeable — is the earlier of the date the invoice is issued or the date payment is received. This means VAT is due whether or not the tenant has paid, based on the invoice date. A landlord who issues an invoice on the first of the month and receives payment on the thirtieth still has a VAT obligation for that month.
Any landlord complying with rent VAT rules for Kenya landlords must maintain accurate records of every invoice issued, every payment received, and every input tax claim made. The records must support the figures reported in the VAT return and be available for inspection by KRA.
The eTIMS Requirement and Digital Compliance
The rent VAT rules for Kenya landlords conversation has acquired a digital compliance dimension. KRA has introduced requirements for electronic tax invoicing through eTIMS. Landlords earning income beyond salary, whether from a side hustle or rental property, must issue electronic tax invoices. KRA validation begins with declared income and expenses cross-checked against eTIMS, withholding tax, and import data.
For VAT-registered landlords, the eTIMS requirement means that every commercial rent invoice must be generated through a compliant system and transmitted to KRA. The invoice must include the supplier’s and customer’s name, address, and PIN, be serially numbered, and show the VAT charged separately.
RentalDesk generates invoices automatically from the lease record, with all the fields required for compliance. The system maintains a complete audit trail of every invoice issued, every payment received, and every input tax claim made. When KRA requires inspection, the landlord has the records available rather than reconstructing them from bank statements and WhatsApp messages.
Common VAT Compliance Mistakes Landlords Make
The rent VAT rules for Kenya landlords journey has predictable failure modes. Failing to register when the threshold is crossed is the most expensive. KRA can backdate the 16% VAT liability, and the landlord pays the tax out of pocket along with penalties and interest.
Treating commercial rent as residential is the second. A landlord who lets an office space to a business but declares the income under the residential MRI regime is under-declaring and misclassifying. KRA audits lease agreements and can reclassify the income retrospectively.
Charging VAT on residential rent is the third. Residential rent is exempt. A landlord who charges VAT on residential rent is overcharging tenants and potentially exposing themselves to refund claims.
Failing to apportion mixed-use properties is the fourth. A landlord with both residential and commercial units must separate the income streams and apply the correct treatment to each.
Missing the monthly filing deadline is the fifth. VAT returns are due by the 20th of the following month. Late filing attracts penalties and interest.
How RentalDesk Simplifies VAT Compliance
RentalDesk is built specifically for the Kenyan market and supports VAT compliance for landlords with commercial properties.
The platform maintains separate records for residential and commercial units, so the VAT treatment is applied correctly to each. Commercial rent invoices are generated with VAT itemised separately, and the monthly VAT return figures can be extracted from the same records. Residential rent invoices are generated without VAT, reflecting the exempt status.
RentalDesk also generates the rent register, the collection summary, and the financial reports that support VAT filing. The figures that appear in the VAT return are drawn from the same verified ledger used for daily operations. Nothing has to be reconstructed.
For mixed-use properties, the platform supports the apportionment of input tax between taxable and exempt supplies. The landlord can see at a glance which portion of the portfolio is commercial and which is residential, and the reports reflect the correct VAT treatment for each.
How to Get Started
Implementing VAT-compliant rental management with RentalDesk is straightforward.
Step 1: Sign up. Visit RentalDesk and create your account. Choose a plan that matches your portfolio size.
Step 2: Classify your properties. Record each unit as residential or commercial. This determines the VAT treatment.
Step 3: Record your lease terms. Enter rent amounts, due dates, billing frequencies, and VAT applicability for each tenancy.
Step 4: Configure M-Pesa collection. Connect your Paybill so that payments reconcile automatically, with VAT correctly applied to commercial rent.
Step 5: Run a pilot billing cycle. Process one full month for a commercial unit and confirm that VAT is itemised correctly.
Step 6: Go live. Roll out to the full portfolio and review the VAT report each month before filing.
The Future of Rent VAT in Kenya
The rent VAT rules for Kenya landlords landscape is moving toward greater digitisation and enforcement. KRA validation through eTIMS, the Electronic Rental Income Tax System, and cross-referencing with land registry data is making it harder for landlords to under-declare or misclassify rental income. The Finance Act 2026 introduced a self-assessment regime for non-resident rental income tax at 30% on gross rent, further expanding the compliance net.
The landlords who adopt structured VAT compliance early will not simply have tidier records. They will have protection against backdated assessments, penalties, and interest. They will have the documentation to demonstrate compliance when KRA asks questions. And they will have the systems in place to grow their commercial portfolios without triggering a compliance crisis.
RentalDesk provides the structured platform that makes rent VAT compliance for Kenya landlords manageable — not as a year-end scramble, but as a continuous, verified record that separates residential from commercial, applies the correct treatment to each, and generates the reports that KRA expects to see.
- Rent VAT rules for Kenya landlords
- Rent VAT rules for Kenya landlords
- Rent VAT rules for Kenya landlords
- Rent VAT rules for Kenya landlords
- Rent VAT rules for Kenya landlords
- Rent VAT rules for Kenya landlords
- Rent VAT rules for Kenya landlords
- Rent VAT rules for Kenya landlords
- Rent VAT rules for Kenya landlords