KRA rental income tax Kenya guide for landlords is no longer a document you read once and file away. It is the operating manual for a compliance regime that has moved from voluntary to mandatory within a single year. The Kenya Revenue Authority launched the Electronic Rental Income Tax System in April 2025, and the draft Income Tax (Residential Rental Income Tax) Regulations 2026, open for public comment until 25 May 2026, propose making registration on that platform compulsory for every landlord within the monthly rental income band.
A person subject to residential rental income tax is required to keep records necessary for the determination and ascertainment of the tax in accordance with the Tax Procedure Act, 2015, and to submit a return and pay the tax due on or before the 20th day of the month immediately following the month in which the rent was received. Understanding the KRA rental income tax Kenya guide for landlords is therefore the difference between operating with confidence and operating with a retrospective liability.
What the Monthly Rental Income Regime Actually Is
The KRA rental income tax Kenya guide for landlords begins with the regime itself. Monthly Rental Income tax, commonly called MRI, was introduced through the Finance Act 2015 and came into effect on 1 January 2016. It is a simplified tax on residential rental income, payable by a resident person — individual or company — on rental income accrued or derived in Kenya from the use or occupation of residential property.
The regime covers landlords earning rental income between KSh 288,000 and KSh 15 million per year. The government reduced the MRI rate from 10% to 7.5% of gross income with effect from 1 January 2024. The current rate is 7.5% on gross rent received, and it is a final tax. No expenses, losses, or capital deductions are allowed for deduction from the gross rent.
Any landlord working through a KRA rental income tax Kenya guide for landlords should understand that the word “final” matters. Income subject to MRI is not liable to any other tax under the Income Tax Act. You do not declare this rental income again in your annual return. The 7.5% settles the obligation.
Who Must File Under the MRI Regime
The KRA rental income tax Kenya guide for landlords applies to resident persons earning gross annual residential rental income between KSh 288,000 and KSh 15 million. That is roughly KSh 24,000 per month at the lower bound.
But the regime has clear boundaries. Rental income from commercial property is exempt from MRI and is taxed under the annual income tax regime instead. Non-resident landlords are excluded from MRI. And landlords earning residential rental income above KSh 15 million per year fall outside MRI and declare the income together with other sources in their annual return.
A landlord may elect, by notice in writing to the Commissioner, not to be taxed under MRI but under the annual income tax regime instead. That election makes sense only if the landlord has substantial deductible expenses — mortgage interest, major repairs, or property management fees — that would reduce the taxable base below what the flat 7.5% produces.
The eRITS Platform and Mandatory Registration
The KRA rental income tax Kenya guide for landlords must address the Electronic Rental Income Tax System, because it is the mechanism through which compliance now flows.
eRITS was launched in April 2025 as part of KRA’s Enterprise Integration and API Management initiative, which aims to enhance efficiency in registration, filing, and payment processes. The platform supports voluntary compliance by integrating with existing Kenyan government digital platforms including eCitizen and GavaConnect. Future integration with Ardhisasa — the National Land Information Management System — is anticipated to boost compliance through geo-referencing and data verification of rental properties, aligning them with taxpayer declarations.
The draft Regulations 2026 formalise the registration obligation. Landlords must register their properties in an electronic system prescribed by the Commissioner, and those who fail to comply will be liable to penalties provided for in the Tax Procedures Act. The Commissioner may by notice require any person to produce books and records relating to the computation of the tax, appear at a specified time and place, or update property details in the prescribed electronic system.
How to Register Your Properties on eRITS
The KRA rental income tax Kenya guide for landlords process starts with registration. Registration is done online via the iTax portal or directly through eRITS. The steps follow a defined sequence.
Under the registration tab, select the option to register property details. There are two sections: Section A, which contains the landlord’s auto-filled details, and Section B, which the taxpayer completes. You select the type of property — new property, update property, or deregister property — and then provide the KRA PIN of a tenant of the property. The system auto-populates the tenant’s name. You enter the property details and an estimated monthly rental income, click add, add any remarks, and submit. You receive an acknowledgement receipt for the registered property details.
Any landlord following a KRA rental income tax Kenya guide for landlords should register every residential property in the portfolio, not just the largest ones. The registration is applied at the individual unit level, and partial registration creates gaps that surface during audit.
Filing Monthly Returns and Meeting the 20th Deadline
The KRA rental income tax Kenya guide for landlords imposes a monthly filing and payment obligation that catches many landlords unprepared, because they expect an annual deadline. There is no annual deadline for MRI. The return is submitted and the tax paid on or before the 20th of the month immediately following the month in which the rent was received. Rent received in January is declared and tax paid on or before 20 February.
Filing is done through iTax or eRITS. Under the returns tab, select the obligation “Income Tax – Rental Income”. Section A asks whether you are filing an original or amended return. Section B shows the total number of properties auto-populated from your registration records. You enter the monthly rental income and the tax is computed automatically at 7.5%. Any rental withholding certificates and credits auto-populate and factor into the final tax due.
The KRA rental income tax Kenya guide for landlords must also address payment. After filing, you generate a Payment Registration Number on iTax, choose the tax head “Income Tax – Rent”, and pay via bank or through M-Pesa using the PRN. The payment must clear by the 20th.
Penalties for Late Filing and Late Payment
The KRA rental income tax Kenya guide for landlords cannot ignore penalties, because they compound quickly and are enforced automatically.
Late filing of MRI returns attracts a penalty of KSh 2,000 or 5% of the tax due, whichever is higher, for individuals. For corporates, the penalty is KSh 20,000 or 5% of the tax due, whichever is higher. Late payment attracts a penalty of 5% of the tax due, and late payment interest runs at 1% per month or part of the month until the tax is fully paid.
For non-resident landlords under the new final withholding regime, failure to pay the required tax on time attracts a 5% penalty on the unpaid tax plus 1% monthly interest until settled. An appointed withholding agent who fails to deduct and remit withholding tax faces a penalty of 10% of the tax due, with interest at 1% per month capped at the value of the principal tax, and the withholding tax penalty limited to KSh 1 million.
Any landlord relying on a KRA rental income tax Kenya guide for landlords should treat the 20th as immovable. There is no grace period, and the penalty regime does not distinguish between a landlord who forgot and one who chose not to file.
Non-Resident Landlords: The 30% Final Tax
The KRA rental income tax Kenya guide for landlords has a separate chapter for landlords living abroad, because the rules changed materially under the Finance Act 2026.
Non-resident property owners now pay 30% of gross rental income before expenses are deducted, under a final non-resident rental income tax introduced under Section 6B. The regime came into force on 1 July 2026. A Kenyan landlord living abroad who earns KSh 100,000 in monthly rent pays KSh 30,000 in tax, leaving KSh 70,000 after tax. Non-residents do not qualify to claim any expenses, and the tax is final.
Relatives, agents, and property managers may be required to withhold and remit tax on behalf of non-resident property owners, and payment is due by the 20th of the month following the month in which the rental income is earned unless a resident agent is withholding on their behalf.
Any landlord researching a KRA rental income tax Kenya guide for landlords from outside Kenya should confirm their residency status with a tax adviser before filing. The 30% rate applies to landlords living outside Kenya, while landlords living in Kenya generally pay 7.5% of gross residential rent. Filing under the wrong regime creates a liability that surfaces years later with interest.
Commercial Property: A Different Regime Entirely
The KRA rental income tax Kenya guide for landlords must separate residential from commercial, because the treatment is entirely different.
Rental income from commercial property is exempt from MRI and is assessed under the annual income tax regime. Landlords with commercial tenants must prepare a profit and loss account to ascertain the gains for the year, and expenses are allowable.
Allowable deductions under the annual regime include land rent and rates, regular repairs and maintenance that do not increase the existing rent, structural alterations to maintain existing rent, insurance premiums paid to insure the property, and mortgage interest. Where a property has both residential and commercial tenants, expenses claimed under the commercial portion must be apportioned in the same ratio as the commercial rent bears to total income.
A landlord with a mixed portfolio therefore has two computations. The residential portion is taxed at 7.5% of gross under MRI. The commercial portion is taxed under the annual regime with allowable deductions. Any landlord following a KRA rental income tax Kenya guide for landlords for a mixed portfolio should separate the income streams from the first day of the financial year.
Records You Must Keep
The KRA rental income tax Kenya guide for landlords requires records, and this is where most landlords fail when an audit arrives.
A person subject to residential rental income tax is required to keep records necessary for the determination and ascertainment of the tax in accordance with the Tax Procedure Act, 2015. The Commissioner may by notice require any person to produce books and records relating to the computation of the tax or appear at a specified time and place.
In practice, the records KRA expects include a rent register showing every tenant, every property, and every payment received in the period. eTIMS-compliant receipts issued to tenants. Lease agreements for the tenancies that generated the rent. And bank statements or M-Pesa transaction logs showing the rent received. A landlord who cannot produce these records when asked is exposed to assessment on KRA’s own figures.
RentalDesk generates the rent register, the collection summary, and the financial reports from the same verified records used for daily operations. The platform captures M-Pesa payments automatically through Safaricom’s Daraja API with Instant Payment Notification callbacks, matches them to the correct tenant and unit, and maintains a complete audit trail. When KRA requires inspection, the landlord produces records that already exist rather than reconstructing them from bank statements and WhatsApp messages.
How RentalDesk Supports KRA Compliance
RentalDesk is built specifically for the Kenyan market, and KRA compliance sits at the centre of the platform.
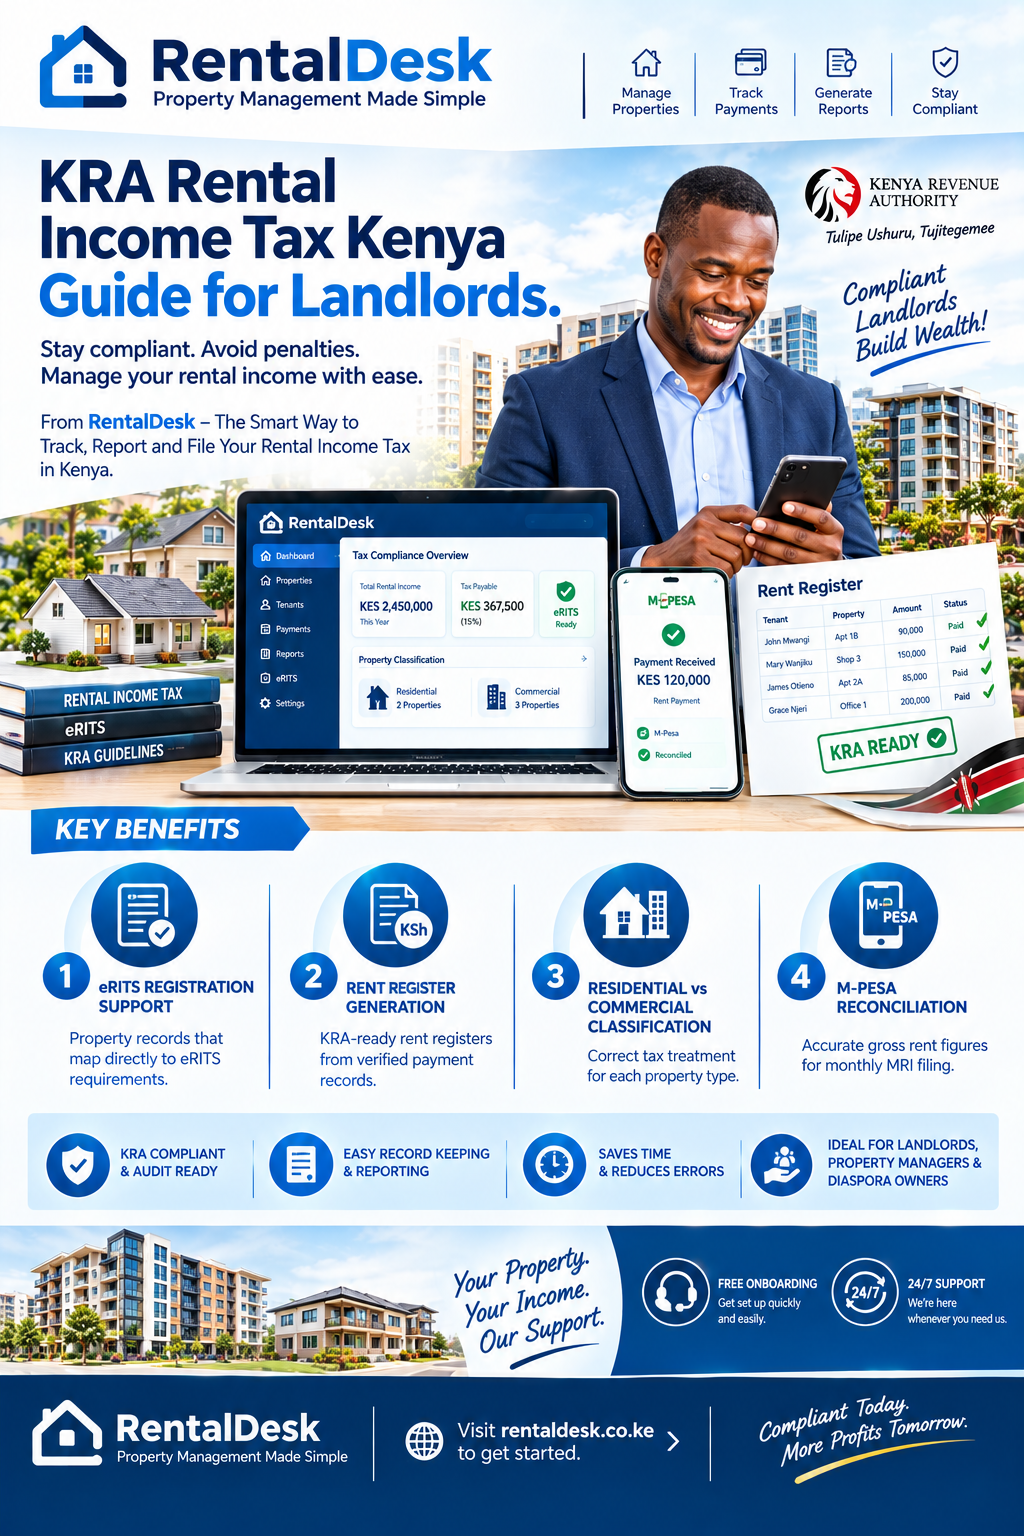
Rent register generation. The platform produces a rent register showing every tenant, property, and payment received in the period, reconciled to the payment ledger.
M-Pesa reconciliation. Payments are matched automatically, so the gross rent figure reported in the MRI return is accurate and defensible.
Expense tracking for commercial property. Where the landlord has commercial tenancies taxed under the annual regime, the platform records and categorises allowable expenses.
Residential and commercial separation. Each unit is classified, so the correct tax treatment is applied and the two computations are kept separate.
eRITS-ready reports. The figures needed for monthly MRI filing are generated from the same verified records used for daily operations.
Role-based access. Landlords, property managers, and accountants see only what their role requires, with every action logged.
Cloud access. RentalDesk is accessible from anywhere, which matters for diaspora landlords filing under the non-resident regime.
Common Compliance Mistakes Landlords Make
The KRA rental income tax Kenya guide for landlords journey has predictable failure modes. Treating the deadline as annual rather than monthly is the first, and it generates a penalty every month until corrected. Failing to register properties on eRITS is the second, and the draft Regulations make that a penalty-bearing omission. Deducting expenses under MRI is the third, because the regime permits none — if you want deductions, you must elect out in writing. Filing under MRI as a non-resident is the fourth, and it is the most expensive, because the 30% final tax applies and KRA is auditing residency. Failing to keep records is the fifth, because an assessment without records is an assessment on KRA’s terms.
How to Get Started
Implementing compliant KRA rental income tax Kenya guide for landlords practices is straightforward with RentalDesk .
Step 1: Sign up. Visit RentalDesk and create your account. Choose a plan that matches your portfolio size.
Step 2: Classify your properties. Record each unit as residential or commercial, and confirm your residency status for tax purposes.
Step 3: Register on eRITS. Use your property records to complete eRITS registration for every residential unit.
Step 4: Configure M-Pesa collection. Connect your Paybill so that payments reconcile automatically and the gross rent figure is always accurate.
Step 5: Record expenses. For commercial property, configure expense categories so allowable deductions are captured throughout the year.
Step 6: Run a pilot filing cycle. Process one month, generate the rent register, and file the MRI return by the 20th.
Step 7: Go live. Roll out to the full portfolio and review the rent register each month before filing.
The Future of Rental Income Tax Compliance in Kenya
The KRA rental income tax Kenya guide for landlords landscape is moving toward digital enforcement. The draft Regulations 2026 propose making eRITS registration mandatory for all landlords within the monthly rental income band. KRA’s integration with Ardhisasa, eCitizen, and GavaConnect will allow cross-referencing of land records against tax declarations. The Finance Act 2026 introduced a final non-resident rental income tax at 30%, extending the compliance net to diaspora landlords. And the penalty regime under the Tax Procedures Act applies automatically.
RentalDesk provides the structured platform that makes the KRA rental income tax Kenya guide for landlords operational — not as a document read once, but as a continuous, verified record that produces the rent register, the payment ledger, and the reports that KRA expects to see.
- KRA rental income tax Kenya guide for landlords
- KRA rental income tax Kenya guide for landlords
- KRA rental income tax Kenya guide for landlords
- KRA rental income tax Kenya guide for landlords
- KRA rental income tax Kenya guide for landlords
- KRA rental income tax Kenya guide for landlords
- KRA rental income tax Kenya guide for landlords